Oct 18, 2026
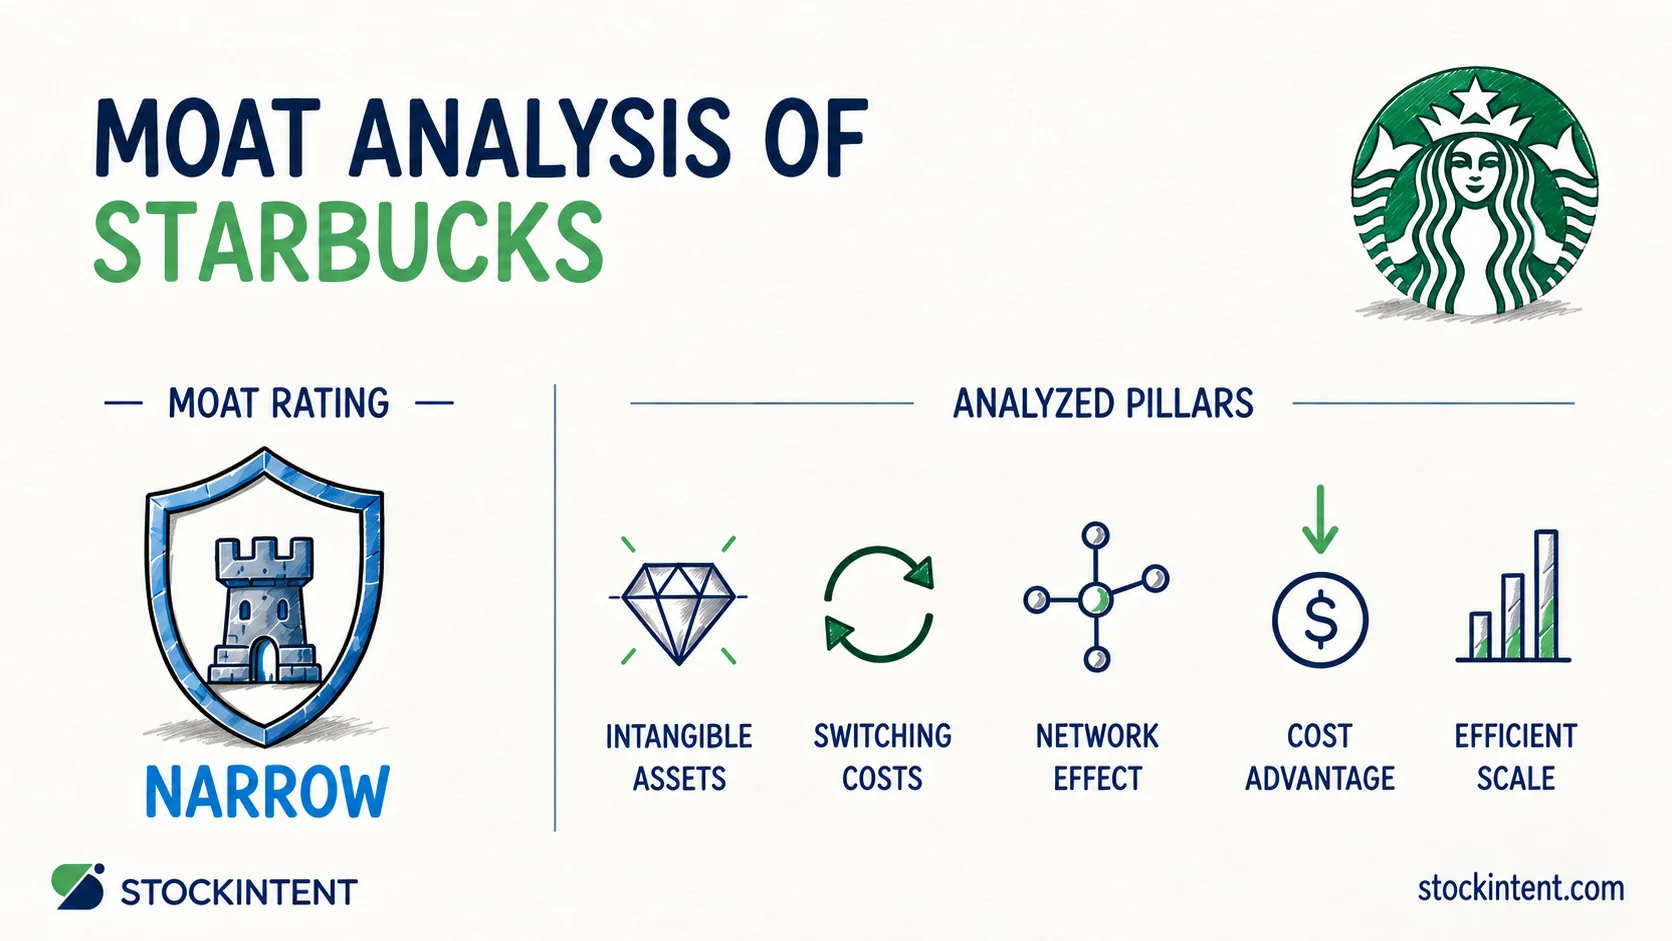
We rate Starbucks as having a narrow economic moat with a stable trend and medium uncertainty. The moat is currently recovering rather than widening outright. It rests primarily on intangible brand assets and switching costs created by the Starbucks Rewards program.
Recent financial results show that the brand continues to pull in customers. In Q3 fiscal 2026, Starbucks reported global comparable store sales growth of 7.9%. North America comps climbed 8.1%, supported by a 4.5% rise in customer traffic.
Here is our assessment of the business:
Economic moats matter because durable competitive advantages let companies compound cash flows across market cycles. Below, we examine each pillar, assess how that advantage translates into reported performance, and evaluate the risks ahead.
We assess Starbucks across five traditional moat pillars: network effects, switching costs, intangible assets, cost advantage, and efficient scale. Intangible assets anchor the business. Switching costs and cost advantages offer modest support, while efficient scale and network effects play minimal roles.
The brand remains the primary competitive advantage for Starbucks, and it demonstrates clear economic value. Customers routinely pay a premium over basic drip coffee and gas-station alternatives. The company also requires comparatively modest marketing spend to sustain visit frequency. Investor materials from 2026 attribute sustained demand to brand recognition, store density, and premium market positioning. Because this brand equity supports regular pricing adjustments and repeat foot traffic, we consider it a genuine moat source.
Starbucks Rewards creates meaningful consumer friction. Members store cash balances across physical gift cards and the mobile app, accumulate stars for discounts, and develop order routines that require effort to replicate elsewhere. The program reached 35.6 million 90-day active U.S. members in Q3 fiscal 2026, expanding 4% over the prior year. Starbucks reports that roughly 60% of domestic company-operated sales move through Rewards accounts. A 2026 program redesign added tiered redemption and targeted offers to protect retention. We rate this pillar as moderate because customers face no contractual barriers preventing them from visiting competitors. Habit and location convenience drive this retention rather than true lock-in.
Pro Insight: Most retail commentary treats Starbucks Rewards as a network effect. We view that as a misunderstanding. A true network effect requires that every new participant increases utility for existing users, as seen on digital marketplaces. The 35 millionth Rewards member does not improve drink quality or speed up wait times for anyone else. Rewards operates as a loyalty system, so we classify it strictly under switching costs.
Scale provides clear leverage in green coffee purchasing, bean roasting, and supply-chain logistics. Very few specialty beverage competitors can duplicate that buying power. However, recent margin contraction tied to retail wage increases and volatile green coffee prices demonstrates that this scale has clear limits. A structural cost moat typically yields consistently superior margins across cycles, which Starbucks does not reliably show.
The company operates an extensive retail footprint and holds the leading share in the premium U.S. coffee space. Even so, competitors such as Dutch Bros and Luckin Coffee continue to open units and generate profits within the same regional markets. Heavy market presence raises capital requirements for smaller operators, but it does not block competitors from entering.
Additional customer sign-ups do not improve store experiences or product quality for other patrons. We consider this factor absent from the business model.
Brand equity and the Rewards program generate the vast majority of the company's economic returns. In Q2 fiscal 2026, Starbucks reported a 6.2% increase in global comparable sales, led by a 7.1% gain in the United States. Revenue and net income expanded together year over year for the first time in more than two years. That growth showed high customer retention, with company updates pointing to dedicated patrons visiting four or more times per week.
Management also balanced its pricing power with transaction volumes. Second-quarter gains stemmed primarily from higher transaction counts rather than pure menu price hikes. That balance indicates Starbucks can maintain customer visits even when inflationary pressures hit discretionary budgets.
Operating profitability remains more volatile. GAAP operating margin dropped to 9.9% in Q2 from 11.6% in the prior-year period due to wage investments, product mix shifts, import tariffs, and higher coffee bean prices. Operating margin recovered sequentially to 10.5% in Q3, but a single quarter of improvement does not confirm permanent stabilization.
Direct peer comparisons require some caution here. Heavily franchised operators such as McDonald's post higher margins because their revenue comes largely from royalties and rental fees. Starbucks operates most of its core stores directly, so raw margin comparisons can exaggerate operational weakness. Its structural advantage centers on customer loyalty data, foot traffic, and repeat visits.
We rate the moat trend as stable, though performance diverges sharply by region. The domestic business is gradually strengthening, while the China division faces persistent competitive erosion.
Domestically, operational initiatives are delivering results. Store redesigns are lifting transaction volumes, the revised Rewards program is increasing member activity, and operational turnaround plans are gaining traction. If remodeled locations continue to outpace older formats, the company can widen its customer experience lead over regional rivals.
China presents severe headwinds. Comparable store sales in the region remain soft, promotional discounting has intensified, and local competitors like Luckin Coffee operate larger physical footprints with lower menu prices. CNBC's coverage noted that Starbucks increasingly competes on discounts in China rather than commanding its traditional premium. In the U.S., market data cited by the Butler Eagle suggested that Starbucks' share of total coffee shop spend drifted from 52% in 2023 to 48% by early 2026. While third-party estimates carry margins of error, they highlight growing pressure from drive-thru operators and independent shops.
We monitor several primary indicators to evaluate this moat trend:
We monitor these fundamental operating metrics, including revenue and free cash flow conversion, using our StockIntent watchlist. We track store renovations and international pricing developments through regulatory filings and quarterly earnings calls.
We rate the uncertainty around Starbucks as medium. Our moat thesis relies on steady execution across several ongoing operational changes, which creates a moderate spread between bull and bear operating scenarios.
Several factors help stabilize the business outlook. On the Q3 FY2026 earnings call, management outlined full-year guidance calling for flat-to-modestly higher revenue, consolidated operating margins above 11%, and EPS between $2.55 and $2.65. Adjusted operating margin reached 14.4% during Q3, up 430 basis points year over year according to the company's earnings release. Starbucks also applied roughly $1.8 billion in proceeds from its China joint venture toward debt reduction, lowering leverage to 2.9x. That balance sheet management limits downside balance-sheet risk.
Other variables keep the potential range of outcomes wider. Changing consumer spending habits, commodity price swings, and potential import tariffs all introduce volatility. Furthermore, if domestic foot traffic slows or the Boyu joint venture fails to halt market share losses in China, earnings could miss expectations.
Starbucks maintains a narrow economic moat supported by a stable trend and medium uncertainty. The core business demonstrates durable customer loyalty. High repeat visits and massive Rewards adoption protect baseline revenues, but unresolved margin pressures and competitive losses in China prevent us from assigning a wide moat rating.
Moving forward, we are watching two main developments. First, we want to see whether U.S. transaction growth can continue without reliance on discounting. Second, we will monitor whether the China joint venture can defend its local margins against low-cost domestic competitors.
Valuation requires personal discipline. A high-return business undergoing operational updates requires an adequate margin of safety before allocating capital. An economic moat helps describe business durability, but it does not specify an entry price. Future returns will depend heavily on management's operational execution over the coming years.
This analysis is for informational and educational purposes only and is not investment advice.
Start your 7-day free trial and find quality compounders faster.
— StockIntent Score ╌ S&P 500